| Company | Oct 25 | Nov 25 | Dec 25 | Jan 26 | Feb 26 | Mar 26 | Apr 26 | May 26 | Jun 26 | Jul 26 | Aug 26 | Sep 26 | 12-Mo |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| DDOG | +14% | -2% | -15% | -5% | -13% | +5% | +12% | +87% | +5% | +3% | -12% | +13% | +89% |
| DT | +4% | -12% | -3% | -12% | -6% | +3% | -2% | +18% | +3% | +1% | +23% | +5% | +19% |
| ESTC | +6% | -21% | +7% | -13% | -21% | -4% | -7% | +39% | -12% | +15% | +48% | -9% | +5% |
| S | +1% | -9% | -7% | -7% | -6% | -2% | +10% | +17% | +3% | +12% | +16% | +5% | +32% |
| NET | +18% | -21% | -2% | -10% | -3% | +20% | -1% | +18% | +1% | +14% | +9% | +15% | +64% |
| SNOW | +22% | -9% | -13% | -12% | -13% | -10% | -10% | +87% | -0% | +15% | +13% | -0% | +46% |
Source: Yahoo Finance monthly adjusted close.
Quick Thesis
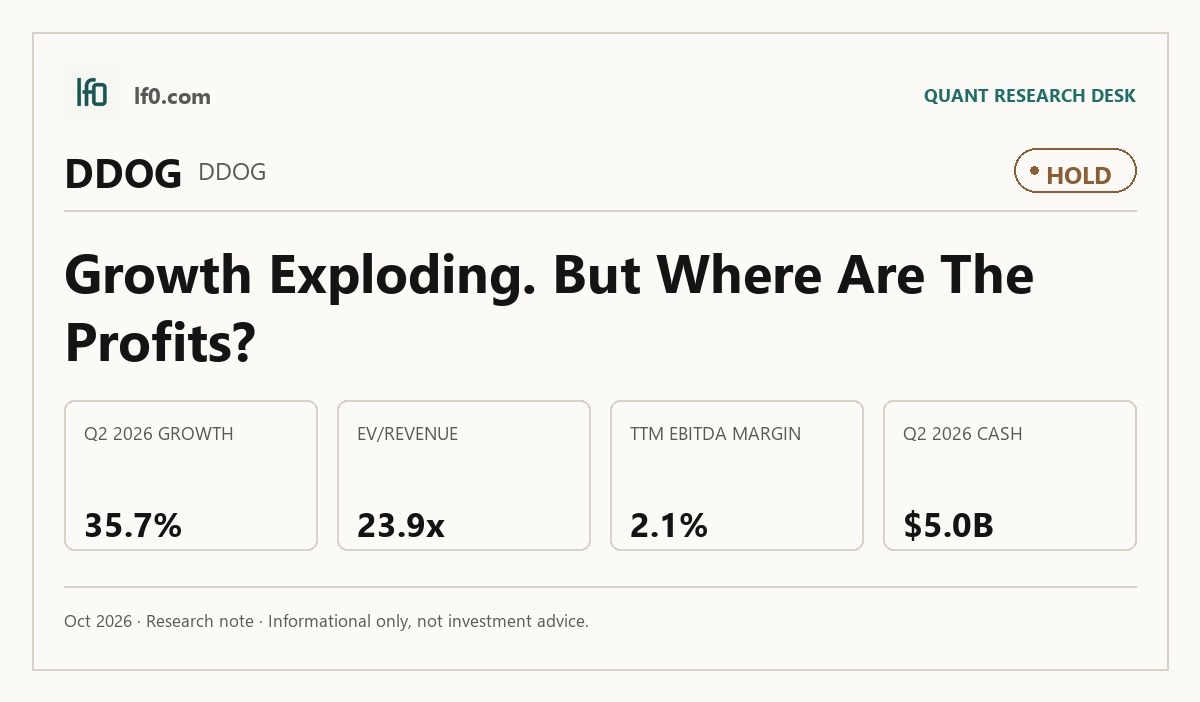
- Rated hold because Datadog is still scaling, but the valuation already discounts a lot of that progress.
- Strongest point: 35.6% TTM revenue growth, with revenue at $1,121.5M in Q2 2026.
- Biggest risk: 23.9x EV/revenue leaves little cushion if growth or margin conversion slows.
- Valuation is rich versus peers, though not wildly out of line with the fastest growers.
- I would turn more constructive if operating margin moves above 5.0%, showing real earnings leverage.
Executive Summary
Rating: HOLD | DDOG
We’ll begin tracking this call’s performance since publication once sufficient adjusted-close data is available.
I would put my rating as a Hold because Datadog’s platform breadth and 35.6% TTM revenue growth are real strengths, but the stock already trades at 23.9x EV/revenue and 92.1x forward P/E, so the market is paying for a lot of future execution. In my view, the key question is not whether the business is good — it is — but whether it can convert that growth into materially higher operating profit fast enough to justify the multiple.
The moat is stronger than it was a few years ago because Datadog now spans observability, security, and AI operations in one workflow, and that breadth is hard to replicate quickly. Even so, TTM operating margin is only 0.7% and FCF yield is 1.1%, which tells me the economics are still early and the valuation is doing most of the work.
I would raise my rating more toward a Buy if operating margin moves above 5.0%, meaning the company is turning gross profit into durable earnings rather than just scaling revenue. If growth stays above 30.0% for the next two quarters and margins keep improving, I would have more confidence that the current premium is being earned rather than merely assumed.
Company Profile
Datadog is a cloud software company focused on observability, security, and AI operations. It sells a subscription platform used to monitor infrastructure, application performance, logs, user experience, cloud security, service management, and product analytics, with revenue expanding as customers add hosts, data volume, and modules.
The company was founded in 2010 and launched Infrastructure Monitoring in 2012. Since then it has broadened into Log Management, APM, Cloud SIEM, Cloud Security, LLM Observability, OnCall, Product Analytics, and Bits AI SRE, so the product set now reaches well beyond the original monitoring use case. As of December 31, 2025, Datadog served about 32,700 customers in over 160 countries and employed about 8,100 people across 35 countries.
Economic Moat
Business Model
The core advantage is the breadth of Datadog’s platform. It combines infrastructure monitoring, application performance monitoring, log management, user experience monitoring, cloud security, service management, and AI-driven incident response in one self-service system, with a common data model and over 1,000 integrations according to their SEC 10-K.
I feel that this breadth is hard to copy quickly because the product is already embedded across development, operations, security, and business teams, not just one buyer group. The self-service deployment, cloud-agnostic design, and “single pane of glass” correlation across metrics, traces, logs, sessions, and security signals make the platform stickier than a point solution.
The moat has also widened as Datadog has moved from a monitoring tool into a broader operating layer. Bits AI SRE Agent, Event Management, and LLM Observability extend the platform into automated troubleshooting, which matters because it pushes Datadog deeper into daily workflows rather than leaving it as a passive dashboard.
Business & Operating Risks
The main disclosed risk is that Datadog depends on customer IT budgets, so a slowdown in spending can hit both new usage and expansion inside existing accounts. That risk is not abstract: the filing explicitly warns about reductions in information technology spending and elevated interest rates, both of which can make customers more cautious about adding modules or increasing usage.
Cybersecurity and reliability are also material. According to the risk factors in their SEC 10-K, an unauthorized third party accessed a number of Datadog source code repositories in April 2025 through compromised employee credentials, and the platform also experienced widespread outages across multiple products and regions in March 2023. Those events do not break the moat, but they do test it, because trust and uptime are part of the product itself.
Datadog also faces a heavier compliance load across the European Union and the United Kingdom, including GDPR, NIS2, the EU AI Act, and cross-border data transfer rules. In my view, these risks pressure the moat at the edges rather than at the core: they do not undermine the platform’s breadth, but they can slow expansion and raise operating costs if execution slips.
Management Discussion & Analysis
Management is still behaving like a growth company, not a harvest story. Revenue reached $3,966.7M in TTM terms, and the company kept investing in sales, product development, and international coverage, which tells me leadership is prioritizing platform expansion over near-term margin maximization.
That stance is consistent with the risk profile above. The company is responding to budget and security pressure by broadening the product set and deepening customer usage, but the April 2025 source-code incident remains unresolved in the sense that it is a live operating risk, not a one-time historical footnote.
The customer data supports the strategy. Customers with annual run-rate revenue of $100,000 or more rose to about 4,310 in FY2025 from 3,610 in FY2024, and customers with ARR of $1.0 million or more rose to about 603 from 462, so the land-and-expand model is still working. At the same time, operating expenses rose faster than revenue in FY2025, which means the company is still buying scale rather than harvesting it.
Recent Events
The most important recent event was the redomiciliation from Delaware to Nevada, approved and completed on April 21, 2026. That is a governance change rather than an operating one, so it does not alter the product moat, but it does show management is willing to use corporate structure as part of its strategic toolkit.
Datadog also expanded its board on February 26, 2026 by appointing Dominic Phillips and increasing the board to 11 members. I view that as a mild positive for oversight, although it is not a substitute for stronger operating leverage.
The February 10, 2026 and May 7, 2026 8-Ks were routine earnings releases, so they do not change the moat picture on their own. Taken together, the recent filings leave the structural thesis intact, but they do not yet show a new catalyst that would materially strengthen it.
Financial Analysis
Growth
DDOG — Financial Growth (Quarterly, USD Mil)
| Metric | 2025-06-30 | 2025-09-30 | 2025-12-31 | 2026-03-31 | 2026-06-30 |
|---|---|---|---|---|---|
| REVENUE (USD Mil) | 826.8 | 885.7 | 953.2 | 1,006.4 | 1,121.5 |
| EBIT (USD Mil) | 7.5 | 37 | 60.6 | 61 | 53.9 |
| EBITDA (USD Mil) | 20.3 | 52.1 | 77.3 | 78.9 | 73.4 |
| NET INCOME (USD Mil) | 2.6 | 33.9 | 46.6 | 52.6 | 44.6 |
| DILUTED EPS | 0 | 0.1 | 0.1 | 0.1 | 0.1 |
Source: Yahoo Finance — Quarterly Financial Statements
Datadog’s quarterly revenue rose from $826.8M in Q2 2025 to $1,121.5M in Q2 2026, and that is the cleanest sign that the business is still compounding at a healthy pace. The latest quarter was also stronger than the prior quarter’s $1,006.4M, so this was not a step-down; it was another sequential increase on top of already strong growth.
EBITDA moved from $20.3M to $73.4M over the same period, which tells me operating leverage is improving as the top line scales. That matters because the moat only becomes more valuable if growth starts to fund earnings, not just more revenue.
Profitability
DDOG — Profitability (TTM)
| Metric | TTM |
|---|---|
| Operating Margin (TTM) | 0.7% |
| Net Margin (TTM) | 4.5% |
| Return on Assets (TTM) | 0.2% |
| Return on Equity (TTM) | 4.7% |
| Gross Margin (TTM) | 79.5% |
| EBITDA Margin (TTM) | 2.1% |
Source: Yahoo Finance — Trailing Twelve Months (TTM)
TTM gross margin was 79.5%, which confirms the core software model is still very attractive before overhead. The problem is below the gross line: TTM operating margin was only 0.7% and EBITDA margin was 2.1%, so sales and product spending are still absorbing most of the gross profit.
Net margin of 4.5% is better than operating margin, which suggests non-operating items are helping reported earnings, but the absolute level is still thin for a company of this scale. Return on assets was 0.2% and return on equity was 4.7%, so capital efficiency is improving, but it is not yet strong enough to make the valuation look cheap.
Valuation
DDOG — Valuation Multiples
| Metric | Value |
|---|---|
| Current Share Price (USD) | 273.9 |
| Market Cap (USD Mil) | 98,333 |
| Enterprise Value (USD Mil) | 94,625 |
| Trailing P/E | 558.9 |
| Forward P/E | 92.1 |
| Price/Sales (TTM) | 24.8 |
| Price/Book (mrq) | 22.5 |
| EV/Revenue | 23.9 |
| EV/EBITDA | 1,141.5 |
| Beta (5Y Monthly) | 1.49 |
| FCF Yield % (TTM) | 1.1% |
| Forward EPS (USD) | 3 |
| Analyst Target Price – Low (USD) | 158 |
| Analyst Target Price – Mean (USD) | 286.3 |
| Analyst Target Price – High (USD) | 340 |
| # Analyst Opinions | 46 |
Source: Yahoo Finance
Datadog screens as a premium software name. It trades at 23.9x EV/revenue, 24.8x price/sales, 558.9x trailing P/E, and 92.1x forward P/E, while FCF yield is only 1.1% and beta is 1.49, so investors are paying up for growth and accepting above-market volatility.
On my read, fair value sits in a wide range because the business has real quality but still modest margins. Using the peer EV/revenue range and Datadog’s own revenue base, I would frame fair value roughly around the current area rather than at a deep discount, which is why I do not see a clear mispricing on the low side. The analyst set is meaningful at 46 opinions, and the $158 low, $286 mean, and $340 high imply that my view sits slightly below consensus on the upside case because I weight the thin 0.7% operating margin more heavily than the market appears to.
Forward EPS is $2.97, and that is not expensive in isolation, but it is expensive relative to the current margin structure. On a like-for-like basis, Datadog’s earnings power is still behind the best cash generators in software, so the stock is being priced more on future margin expansion than on today’s EPS base.
Leverage
DDOG — Leverage & Coverage (Quarterly)
| Metric | Value |
|---|---|
| Total Debt/Equity % (mrq) | 29.3 |
| Current Ratio (mrq) | 3.2 |
| Total Debt (mrq, USD Mil) | 1,277.8 |
| Operating Cash Flow (TTM, USD Mil) | 1,229 |
| Levered Free Cash Flow (TTM, USD Mil) | 1,051.4 |
| Net Debt/EBITDA (TTM) | -44.7 |
| FCF Margin % (TTM) | 26.5% |
Source: Yahoo Finance — Quarterly Financial Statements
The balance sheet is a strength. Total debt was $1,278M, current ratio was 3.2x, and total cash was $4,985.4M, so Datadog has more cash than debt and plenty of liquidity to keep investing.
Operating cash flow was $1,229M and levered free cash flow was $1,051.4M, which means the business is converting earnings into cash efficiently. Net debt/EBITDA was -44.7x and FCF margin was 26.5%, so refinancing risk is low and the company has room to absorb a slowdown without needing outside capital.
Insider Activity
The insider record is one-sided. I see 0 open-market purchases and 367 open-market sales totaling $551.1M from 2025-01-08 to 2026-06-04, and that is a meaningful negative signal because the selling is broad rather than isolated to one person.
The visible sample includes sales by directors and senior executives, which weakens the alignment signal for outside shareholders. I would not overread any single trade, but the pattern is hard to call constructive.
Comparable Analysis
Growth
| Company | Revenue TTM (USD Mil) | Revenue Growth YoY % | EBITDA TTM (USD Mil) | Diluted EPS TTM |
|---|---|---|---|---|
| DDOG | 3,966.7 | 35.6% | 82.9 | 0.5 |
| DT | 2,095.6 | 16.2% | 291.4 | 0.5 |
| ESTC | 1,802.2 | 15.1% | -22.3 | 3.5 |
| S | 1,098.7 | 20.6% | -237.8 | -1 |
| NET | 2,512.3 | 35.9% | -3.6 | -0.6 |
| SNOW | 5,434.6 | 35.1% | -1,036.3 | -3.2 |
Source: Yahoo Finance
Datadog’s revenue growth of 35.6% TTM is ahead of DT at 16.2%, ESTC at 15.1%, and S at 20.6%, while it is roughly in line with NET at 35.9% and SNOW at 35.1%. That means Datadog is a co-leader, not a lone outlier, so the market is paying a premium for growth that several peers also deliver.
Valuation
| Company | Current Share Price (USD) | Trailing P/E | Forward P/E | EV/Revenue | EV/EBITDA | Price/Sales (TTM) | Price/Book (mrq) | Market Cap (USD Mil) | Enterprise Value (USD Mil) | Beta (5Y Monthly) | FCF Yield % (TTM) | Forward EPS | Analyst Target Price – Low | Analyst Target Price – Mean | Analyst Target Price – High | # Analyst Opinions |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| DDOG | 273.9 | 558.9 | 92.1 | 23.9 | 1,141.5 | 24.8 | 22.5 | 98,333 | 94,625 | 1.49 | 1.1% | 3 | 158 | 286.3 | 340 | 46 |
| DT | 57.7 | 115.5 | 25.2 | 7.5 | 54 | 8 | 6.8 | 16,687 | 15,737 | 0.74 | 3.3% | 2.3 | 42 | 60 | 74 | 34 |
| ESTC | 91.7 | 26.2 | 23.2 | 4.9 | -393.5 | 5.3 | 7.4 | 9,628 | 8,762 | 1.04 | 5.2% | 4 | 75 | 110.7 | 130 | 26 |
| S | 23.8 | — | 51.5 | 6.9 | -32 | 7.5 | 5.7 | 8,270 | 7,614 | 0.77 | 3.6% | 0.5 | 17.5 | 24.4 | 28 | 30 |
| NET | 347.3 | — | 207.2 | 49 | -34,079.2 | 49.2 | 76.3 | 123,659 | 123,026 | 1.66 | 0.6% | 1.7 | 160 | 336.8 | 400 | 31 |
| SNOW | 339.6 | — | 112.7 | 22.1 | -115.9 | 22 | 55.7 | 119,797 | 120,087 | 1.33 | 1.5% | 3 | 110 | 425.1 | 525 | 48 |
Source: Yahoo Finance
Datadog trades at 23.86x EV/revenue, 558.9x trailing P/E, 92.1x forward P/E, and 24.8x price/sales, versus DT at 7.5x EV/revenue and 25.2x forward P/E, ESTC at 4.9x and 23.2x, S at 6.9x and 51.5x, NET at 49.0x and 207.2x, and SNOW at 22.1x and 112.7x. On FCF yield, Datadog’s 1.1% trails DT, ESTC, S, and SNOW, which tells me the stock is priced for better monetization than the cash yield currently shows.
That premium is easier to justify because Datadog’s leverage is much cleaner than most peers. In other words, the market is paying not just for growth, but for growth with a stronger balance sheet and better cash conversion than names like NET and SNOW.
Profitability
| Company | Operating Margin (TTM) | Net Margin (TTM) | Return on Assets (TTM) | Return on Equity (TTM) | Gross Margin (TTM) | EBITDA Margin (TTM) |
|---|---|---|---|---|---|---|
| DDOG | 0.7% | 4.5% | 0.2% | 4.7% | 79.5% | 2.1% |
| DT | 12.9% | 7.2% | 4.2% | 5.9% | 81.6% | 13.9% |
| ESTC | -0.6% | 20.8% | -0.6% | 33.1% | 75.6% | -1.2% |
| S | -22.7% | -31.0% | -7.6% | -23.0% | 72.5% | -21.6% |
| NET | -7.6% | -8.2% | -2.0% | -14.4% | 72.6% | -0.1% |
| SNOW | -17.0% | -20.1% | -9.0% | -48.1% | 67.0% | -19.1% |
Source: Yahoo Finance
Datadog’s 79.5% gross margin is below DT’s 81.6% but above ESTC’s 75.6%, S’s 72.5%, and SNOW’s 67.0%. Its 0.7% operating margin and 2.1% EBITDA margin are still far below DT’s 12.9% and 13.9%, which tells me Datadog has the revenue quality but not yet the operating discipline of the best profitable peer.
Leverage
| Company | Total Debt/Equity % (mrq) | Current Ratio (mrq) | Total Debt (mrq, USD Mil) | Operating Cash Flow TTM (USD Mil) | Free Cash Flow TTM (USD Mil) | Net Debt/EBITDA (TTM) | FCF Margin % (TTM) |
|---|---|---|---|---|---|---|---|
| DDOG | 29.3 | 3.2 | 1,277.8 | 1,229 | 1,051.4 | -44.7 | 26.5% |
| DT | 6.5 | 1.2 | 159.3 | 598.4 | 546.5 | -3.3 | 26.1% |
| ESTC | 45.9 | 1.8 | 595.8 | 354.1 | 504.3 | 38.9 | 28.0% |
| S | — | 1.4 | 0 | 57.3 | 296.9 | 2.8 | 27.0% |
| NET | 217.9 | 1.8 | 3,529.3 | 633.4 | 692 | 175.5 | 27.5% |
| SNOW | 128.6 | 0.9 | 2,763.8 | 1,253.2 | 1,739.5 | -0.4 | 32.0% |
Source: Yahoo Finance
Datadog’s 29.3% debt to equity and -44.7x net debt to EBITDA are far cleaner than NET’s 217.9% and 175.5x, SNOW’s 128.6% and -0.4x, and ESTC’s 45.9% and 38.9x. With a 3.2x current ratio and 26.5% FCF margin, Datadog has the strongest balance-sheet flexibility in the group, which supports continued reinvestment without financing risk.
Conclusion
I would put my rating as a Hold because Datadog’s growth is still strong enough to deserve a premium, but the market is already paying for a margin step-up that has not fully arrived. The tension in the case is simple: the moat is real, the balance sheet is strong, and revenue is still compounding, yet TTM operating margin is only 0.7% and the stock already trades at 23.9x EV/revenue.
The bull case is straightforward. If revenue growth stays above 30.0% for the next two quarters, meaning the current reacceleration is durable, and operating margin moves above 5.0%, meaning the business is finally converting gross profit into meaningful earnings, I would move more toward a Buy. That combination would show that Datadog is not just adding customers and modules, but doing so with real operating leverage.
The bear case is just as clear. If revenue growth falls below 25.0% for two straight quarters, I would read that as a sign that expansion is slowing faster than the market expects, and if FCF margin slips below 20.0%, the cash conversion story would no longer support the current valuation. A further deterioration in net retention from the current 120.0% area would also matter, because the model depends on existing customers expanding usage.
For now, I think the bull case is more likely to show up first, but not enough to justify paying up aggressively today. I would wait for either a cleaner margin step-up or a cheaper entry point before moving off Hold.
What to Watch Next
- Revenue growth above 30.0% for two more quarters — would support a move toward Buy.
- Operating margin above 5.0% — would show earnings leverage is finally arriving.
- FCF margin below 20.0% — would weaken the cash-conversion case.
- Net retention slipping from the 120.0% area — would signal weaker expansion inside existing accounts.
- Another security or outage event — would test whether the platform moat is still widening.
What’s your take? I rated Datadog (DDOG) HOLD above — but the goal here is to get this right, not just to publish an opinion. What would you add to this analysis, or which risk or catalyst do you think I’m under- or over-weighting? Tell me in the comments.
Sources
- SEC 10-K Annual Report — filed 2026-02-18
- SEC 8-K Filing (2026-05-07)
- SEC 8-K Filing (2026-04-22)
- SEC 8-K Filing (2026-03-02)
- SEC 8-K Filing (2026-02-10)
- SEC Form 4 Insider Transaction (2026-06-08)
- SEC Form 4 Insider Transaction (2026-06-05)
- SEC Form 4 Insider Transaction (2026-06-04)
- SEC 10-K Annual Report — FY2026
- SEC 10-K Annual Report — FY2025
- SEC 10-K Annual Report — FY2024
- SEC 10-K Annual Report — FY2023
- SEC 10-K Annual Report — FY2022
Data sourced from Yahoo Finance and SEC EDGAR. Not investment advice.
Leave a Comment