| Company | Oct 25 | Nov 25 | Dec 25 | Jan 26 | Feb 26 | Mar 26 | Apr 26 | May 26 | Jun 26 | Jul 26 | Aug 26 | Sep 26 | 12-Mo |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| SYM | +50% | +3% | -29% | -9% | +1% | -3% | +11% | -21% | -3% | -4% | -8% | +6% | -22% |
| STRL | +11% | -9% | -11% | +17% | +20% | -5% | +27% | +67% | -2% | -29% | -21% | +5% | +45% |
| FIX | +17% | +1% | -4% | +22% | +25% | -3% | +33% | -1% | +8% | -13% | -11% | +7% | +101% |
| KNX | +14% | +2% | +15% | +5% | +14% | -8% | +13% | +17% | +3% | -11% | -1% | -7% | +63% |
| GXO | +6% | -10% | +4% | +8% | +11% | -17% | +10% | -12% | +1% | -1% | -5% | -7% | -16% |
| EXPD | -1% | +21% | +2% | +8% | -10% | -1% | +3% | +7% | +4% | +3% | +13% | -3% | +52% |
Source: Yahoo Finance monthly adjusted close.
Quick Thesis
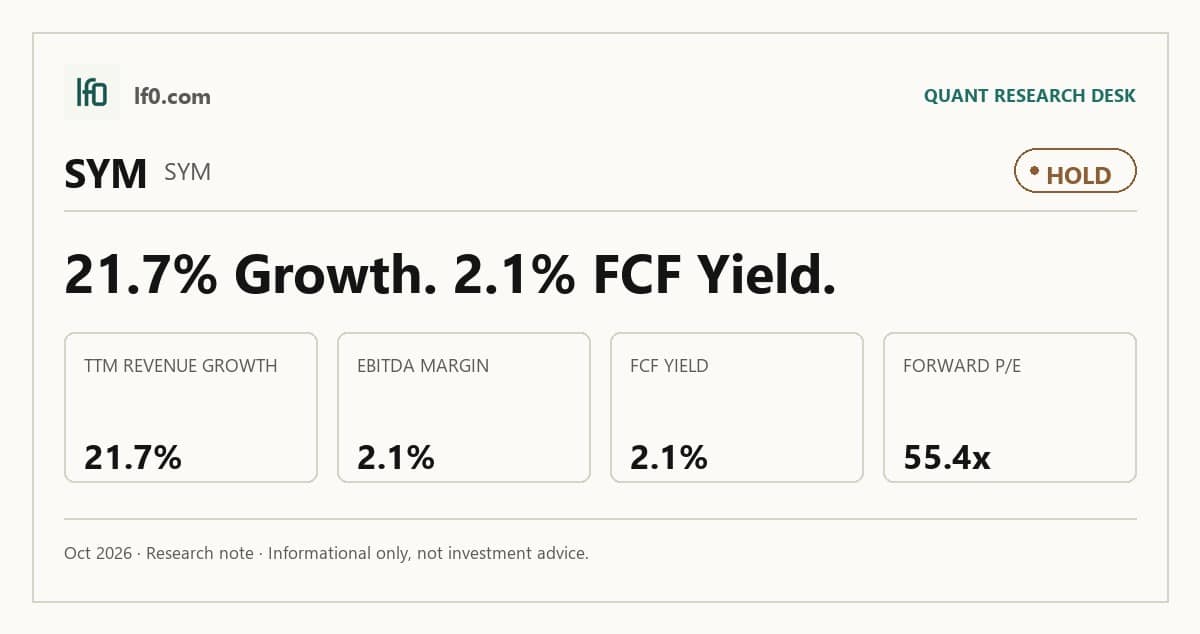
- Rated hold because growth is real, but the valuation already discounts cleaner earnings conversion.
- Revenue reached 720.8M in Q2 2026, while levered free cash flow was 547.6M TTM.
- Main risk: customer concentration, with Walmart still tied to a large share of backlog and revenue.
- Valuation is rich at 9.1x EV/revenue and 55.4x forward P/E.
- I would turn more constructive if operating margin moved into the high single digits.
Performance Since Our Last Call
I last had this name at Hold on 2026-06-14, and the stock has returned +0.8% since then, which keeps the verdict in the Hold range. That performance is consistent with the fresh numbers here: revenue growth is still strong, but margins remain thin and the valuation has not reset enough to create obvious upside. The prior call has not been disproved, but it also has not been rewarded with a rerating. I still see the same tension between execution progress and a demanding multiple.
Executive Summary
Rating: HOLD | SYM
Measured from adjusted close on 2026-06-15 to 2026-10-30. Sell ratings are correct when the stock falls; Hold is tracked as a +/-10% range. Daily-close data, not intraday. Calls are tracked for 182 days from publication, then frozen as a final record.
I would put my rating as a hold because Symbotic is still growing fast, but the stock already prices in a much cleaner earnings ramp than the company has delivered. Revenue reached 720.8M in Q2 2026 and levered free cash flow was 547.6M TTM, so the business is scaling and funding itself, yet the 9.1x EV/revenue multiple and 55.4x forward P/E leave little room for execution slips while operating margin is still only 4.6% TTM.
The key question is whether the Walmart rollout and the broader installed base can convert backlog into durable margin expansion. I would raise my rating more toward a buy if revenue keeps compounding above 700M per quarter and operating margin moves into the high single digits, because that would show the model is turning into earnings power rather than just top-line growth.
Company Profile
Symbotic Inc. develops and deploys warehouse automation systems that process pallets and cases for large retailers, wholesalers, and warehouse-as-a-service customers. Revenue comes from system sales at installation, software maintenance and support over the system life, and limited operation services during customer handoff. Founded in 2006 by Chairman and Chief Executive Officer Richard B. Cohen, the company went public via a SPAC merger in 2022 and has since expanded through long-term programs with Walmart and GreenBox Systems LLC, a joint venture with SoftBank Group for global warehouse automation.
Its systems are installed in active distribution centers across the United States, Canada, and, more recently, Latin America, with R&D centered in Wilmington, Massachusetts and Montreal, Quebec. Symbotic had approximately 1,650 full-time employees as of September 28, 2024 and reported about $22.4B of backlog at that date. The company is listed on Nasdaq under SYM and is financed with equity and customer-backed project commitments rather than a traditional industrial asset base.
Economic Moat
Business Model
The system’s biggest structural edge is its end-to-end warehouse architecture, which combines autonomous mobile robots, AI-enabled software, and proprietary storage logic to automate pallet and case handling at the front end of the supply chain. I feel that this is hard for a well-funded competitor to replicate within 3 years because Symbotic has spent $800M on development, holds over 475 issued patents in 14 countries, and has already proven the system in live deployments with Walmart, C&S Wholesale Grocers, GreenBox, Albertsons, and Target. The current 10-K also shows a second layer of defensibility in the commercial structure: the Walmart Master Automation Agreement, which now covers all of Walmart’s 42 regional distribution centers, and the GreenBox commercial agreement, which commits at least $7.5B over 6 years. Those contracts matter because they turn the technology into a long-duration installed base rather than a one-off pilot.
In my view, the moat is real, but it is still being proven through rollout execution rather than through a broad customer base. That is why the financial analysis below matters so much: the contract structure supports visibility, yet the margin profile still has to catch up.
Business & Operating Risks
Walmart concentration is the clearest disclosed risk because Walmart accounted for approximately 87.0% of total revenue in fiscal 2024 and a significant portion of the $22.4B backlog as of September 28, 2024, so any delay, cancellation, or underperformance in the 42 regional distribution centers under the Master Automation Agreement would hit revenue and backlog at the same time. The filing also says the Walmart agreement added approximately an additional $6.1B to backlog, which means the business is still tied to one customer’s rollout pace rather than a broad base of demand. C&S Wholesale Grocers is the second concentration point: it is an affiliate, and the filing says ongoing Software Maintenance and Support and Operation Services run through September 2029, but there is no guarantee of renewal beyond current contracts, so a non-renewal would remove a named customer that is also tied to management through Richard B. Cohen.
The GreenBox joint venture is a newer risk because the current 10-K says it may fail to realize anticipated benefits, disrupt ongoing operations, or require additional equity, cash, or debt. The restatement issue is more serious for me: management identified material weaknesses because cost of revenue and revenue recognition controls were not designed effectively, which already led to accelerated cost recognition and an overstatement of revenue during the year. That does not break the moat, but it does threaten the trust needed to monetize it cleanly.
Management Discussion & Analysis
Management is still pushing capital into growth and platform buildout rather than near-term cash extraction, and that is the right read on the business at this stage. Revenue from Systems was $1.7B in FY2024, up from $1.1B in FY2023, while Systems in Deployment rose to 44 from 35, so the top line is still being driven by a long deployment cycle. Software Maintenance and Support revenue also rose to $14.2M from $6.6M as Operational Systems under contract increased to 25 from 12, which supports a more durable mix over time even though it is still small relative to Systems revenue.
The cash profile shows the same pattern. Symbotic spent $90.5M on strategic investments, primarily GreenBox, and ended FY2024 with $727.3M of cash and cash equivalents, but operating cash flow was negative $58.1M and free cash flow was negative $102.5M. That tells me management is still buying time for scale, not harvesting it. The restatement disclosure also means management is now being judged not just on rollout speed, but on whether reporting controls can keep pace with a more complex operating model.
Recent Events
The most important development I see is the November 18, 2024 restatement notice. Symbotic said it will restate its first, second, and third quarter fiscal 2024 interim statements because goods and services tied to milestone achievements were expensed too early, which also pulled revenue recognition forward under percentage-of-completion accounting. In my view, that weakens the thesis because it raises execution and reporting-quality risk in a business where milestone timing is central to customer contracts and investor confidence.
The earlier 2024 filings were more constructive. On March 8, 2024, Symbotic completed the underwriters’ option on its equity offering, bringing total net proceeds to about $256M, which strengthens liquidity and gives the company more room to fund deployment. On March 19, 2024, it appointed Maria G. Freve as Vice President, Controller and Chief Accounting Officer, effective April 15, 2024, and her industrial accounting background is a constructive step after the later restatement issue. The capital raise helps the moat by funding rollout, but the restatement reminds me that execution quality still has to be earned.
Financial Analysis
Growth
SYM — Financial Growth (Quarterly, USD Mil)
| Metric | 2025-06-30 | 2025-09-30 | 2025-12-31 | 2026-03-31 | 2026-06-30 |
|---|---|---|---|---|---|
| REVENUE (USD Mil) | 592.1 | 618.5 | 630 | 676.5 | 720.8 |
| EBIT (USD Mil) | -9.4 | -15.3 | 9.2 | 6.1 | 32.9 |
| EBITDA (USD Mil) | 4.8 | -5.2 | 19.3 | 20 | 40.2 |
| NET INCOME (USD Mil) | -3.9 | -3.6 | 2.6 | 2 | 11.7 |
| DILUTED EPS | -0.1 | 0 | 0 | 0 | 0.1 |
Source: Yahoo Finance — Quarterly Financial Statements
Revenue rose from 592M in Q2 2025 to 720.8M in Q2 2026, a 21.7% increase, and the path was steadily upward through $618.5M in Q3 2025, $630M in Q4 2025, and $676.5M in Q1 2026. EBITDA moved faster than revenue, from $4.8M to $40.2M over the same span, while net income improved from a $3.9M loss to $11.7M of profit, so the business is scaling into better earnings leverage. The sharp EBITDA dip to negative $5.2M in Q3 2025 is not explained in the filing context, which is worth flagging because this model still depends on clean milestone execution. Growth is a bull signal, but it only matters if the margin trend keeps following it.
Profitability
SYM — Profitability (TTM)
| Metric | TTM |
|---|---|
| Operating Margin (TTM) | 4.6% |
| Net Margin (TTM) | 0.3% |
| Return on Assets (TTM) | 0.3% |
| Return on Equity (TTM) | 4.4% |
| Gross Margin (TTM) | 21.3% |
| EBITDA Margin (TTM) | 2.1% |
Source: Yahoo Finance — Trailing Twelve Months (TTM)
TTM operating margin was 4.6%, TTM net margin was 0.3%, TTM gross margin was 21.3%, and TTM EBITDA margin was 2.1%. The spread between gross margin and operating margin is wide, which tells me the business is still carrying heavy operating costs relative to revenue, so the core issue is scale and deployment efficiency rather than product economics. TTM return on assets was 0.3% and TTM return on equity was 4.4%, so equity returns are being amplified by leverage rather than by strong asset productivity. The profitability profile is improving, but it is not yet durable enough to justify a premium multiple on its own.
Valuation
SYM — Valuation Multiples
| Metric | Value |
|---|---|
| Current Share Price (USD) | 42.8 |
| Market Cap (USD Mil) | 25,879 |
| Enterprise Value (USD Mil) | 24,159 |
| Trailing P/E | 534.4 |
| Forward P/E | 55.4 |
| Price/Sales (TTM) | 9.8 |
| Price/Book (mrq) | 7.9 |
| EV/Revenue | 9.1 |
| EV/EBITDA | 427.3 |
| Beta (5Y Monthly) | 1.97 |
| FCF Yield % (TTM) | 2.1% |
| Forward EPS (USD) | 0.8 |
| Analyst Target Price – Low (USD) | 38 |
| Analyst Target Price – Mean (USD) | 62.9 |
| Analyst Target Price – High (USD) | 85 |
| # Analyst Opinions | 14 |
Source: Yahoo Finance
Symbotic trades at 42.8 per share, with an EV/revenue of 9.1x, a price/sales ratio of 9.8x, and a forward P/E of 55.4x. That is a rich setup unless revenue keeps compounding and the business converts more of that top line into cash. EV/EBITDA is 427.3x because EBITDA is still very small relative to enterprise value, so that multiple is not a useful cheap-or-expensive signal yet, and the 2.1% FCF yield says the stock is not cheap on cash flow either.
The analyst set is not thin, with 14 opinions, so I do compare my view against it. The target range runs from 38 to 85, with a mean of 62.9, and my fair-value view sits below that mean because I weight the still-thin margin base and the restatement risk more heavily than the consensus appears to. On the analysis here, I would put fair value in a range of roughly $38-$60, which is below the consensus mean but still inside the published target band. I also think the implied earnings path is modest relative to peers: forward EPS is 0.772 for Symbotic, versus $25.4 for STRL, $60.2 for FIX, $4.0 for KNX, $3.5 for GXO, and $8.1 for EXPD, so the market is paying for a much steeper ramp than the current earnings base shows. The rating justification is the same point in shorter form: the stock is not broken, but it is not cheap enough for me to call it a Buy.
Leverage
SYM — Leverage & Coverage (Quarterly)
| Metric | Value |
|---|---|
| Total Debt/Equity % (mrq) | 2.3 |
| Current Ratio (mrq) | 1.3 |
| Total Debt (mrq, USD Mil) | 25.8 |
| Operating Cash Flow (TTM, USD Mil) | 894.4 |
| Levered Free Cash Flow (TTM, USD Mil) | 547.6 |
| Net Debt/EBITDA (TTM) | -30.4 |
| FCF Margin % (TTM) | 20.7% |
Source: Yahoo Finance — Quarterly Financial Statements
Total debt was 25.83M mrq, while total debt/equity was 2.3% mrq and the current ratio was 1.3x mrq, so the balance sheet is lightly levered and has a near-term liquidity cushion. Operating cash flow was 894.4M TTM and levered free cash flow was 547.6M TTM, which shows strong cash conversion rather than earnings being trapped in working capital or capex. Net debt/EBITDA was -30.4x TTM because cash exceeds debt by a wide margin, and FCF margin was 20.7% TTM, a healthy level that supports self-funding. Total cash was 1.7B mrq, which gives the company room to absorb a downturn and makes refinancing risk minimal unless cash burn reverses sharply or a large acquisition changes the capital structure.
The balance sheet is the clearest support for the equity, and it is the main reason the valuation does not look as fragile as the revenue multiple alone suggests. In my view, the leverage profile is a genuine offset to the restatement risk, but it does not erase the need for margin expansion.
Insider Activity
The insider transaction record I see here is one-sided selling: 97 open-market sales, $587.6M total, and no open-market purchases in the 2025-01-01 to 2026-06-01 window. The activity is broad rather than just one seller, with multiple directors and a 10%+ owner transacting, so alignment looks weak at the margin. I would not overread any single sale, but the pattern does not give me confidence that insiders think the stock is obviously cheap.
Comparable Analysis
LF0 has published standalone analyses of these peers: Comfort Systems USA (FIX) (rated Sell).
Growth
| Company | Revenue TTM (USD Mil) | Revenue Growth YoY % | EBITDA TTM (USD Mil) | Diluted EPS TTM |
|---|---|---|---|---|
| SYM | 2,645.8 | 21.7% | 56.5 | 0.1 |
| STRL | 3,438.5 | 90.1% | 714 | 13.9 |
| FIX | 11,228 | 50.3% | 2,002.7 | 40.6 |
| KNX | 7,729.3 | 12.6% | 1,049.9 | 0.3 |
| GXO | 13,641 | 4.3% | 941 | 1.1 |
| EXPD | 12,036 | 32.1% | 1,263.7 | 6.9 |
Source: Yahoo Finance
SYM’s revenue grew 21.7% TTM on $2.6B of revenue, which is well below STRL’s 90.1% and FIX’s 50.3%, but above KNX’s 12.6%, GXO’s 4.3%, and EXPD’s 32.1%. The issue is that SYM’s growth is paired with only $56.5M of EBITDA TTM and $0.1 of diluted EPS TTM, so the market is paying for growth that has not yet translated into earnings power the way it has for STRL, FIX, or EXPD.
Valuation
| Company | Current Share Price (USD) | Trailing P/E | Forward P/E | EV/Revenue | EV/EBITDA | Price/Sales (TTM) | Price/Book (mrq) | Market Cap (USD Mil) | Enterprise Value (USD Mil) | Beta (5Y Monthly) | FCF Yield % (TTM) | Forward EPS | Analyst Target Price – Low | Analyst Target Price – Mean | Analyst Target Price – High | # Analyst Opinions |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| SYM | 42.8 | 534.4 | 55.4 | 9.1 | 427.3 | 9.8 | 7.9 | 25,879 | 24,159 | 1.97 | 2.1% | 0.8 | 38 | 62.9 | 85 | 14 |
| STRL | 514 | 37 | 20.2 | 4.6 | 22.1 | 4.6 | 11.6 | 15,723 | 15,763 | 1.86 | 2.2% | 25.4 | 700 | 836.6 | 1,000 | 7 |
| FIX | 1,709.9 | 42.1 | 28.4 | 5.2 | 29.2 | 5.4 | 18.7 | 60,177 | 58,420 | 1.66 | 3.1% | 60.2 | 1,910 | 2,197 | 2,500 | 8 |
| KNX | 65.1 | 241.2 | 16.2 | 1.7 | 12.5 | 1.4 | 1.5 | 10,600 | 13,096 | 1.21 | 4.6% | 4 | 57 | 85.7 | 100 | 20 |
| GXO | 46.7 | 41.3 | 13.2 | 0.8 | 11.4 | 0.4 | 1.8 | 5,350 | 10,702 | 1.57 | 6.4% | 3.5 | 55 | 68.6 | 90 | 17 |
| EXPD | 193.2 | 28.1 | 23.9 | 2.1 | 19.6 | 2.1 | 11.9 | 25,121 | 24,719 | 1.06 | 3.2% | 8.1 | 100 | 180.9 | 220 | 15 |
Source: Yahoo Finance
SYM trades at 9.1x EV/revenue, 9.8x price/sales, 55.4x forward P/E, and a 2.1% FCF yield, versus STRL at 4.6x, 4.6x, 20.2x, and 2.2%; FIX at 5.2x, 5.4x, 28.4x, and 3.1%; KNX at 1.7x, 1.4x, 16.2x, and 4.6%; GXO at 0.8x, 0.4x, 13.2x, and 6.4%; and EXPD at 2.1x, 2.1x, 23.9x, and 3.2%. Using the peer EV/revenue range of 0.8x to 5.2x on SYM’s $2.6B revenue gives an implied enterprise value of about $2.1B to $13.8B, or roughly $16 to $93 per share after netting SYM’s $1.7B cash and $25.8M debt. That range is wide because the market is still debating how much of the rollout becomes durable earnings, and the balance sheet helps, but it does not fully justify the current multiple.
Profitability
| Company | Operating Margin (TTM) | Net Margin (TTM) | Return on Assets (TTM) | Return on Equity (TTM) | Gross Margin (TTM) | EBITDA Margin (TTM) |
|---|---|---|---|---|---|---|
| SYM | 4.6% | 0.3% | 0.3% | 4.4% | 21.3% | 2.1% |
| STRL | 20.1% | 12.5% | 14.6% | 40.0% | 23.8% | 20.8% |
| FIX | 17.1% | 12.8% | 17.0% | 55.3% | 25.7% | 17.8% |
| KNX | 5.2% | 0.6% | 1.3% | 0.6% | 24.3% | 13.6% |
| GXO | 3.0% | 1.0% | 2.4% | 4.5% | 15.3% | 6.9% |
| EXPD | 10.7% | 7.6% | 15.2% | 42.7% | 13.6% | 10.5% |
Source: Yahoo Finance
SYM’s 4.6% operating margin, 0.3% net margin, 21.3% gross margin, and 2.1% EBITDA margin trail STRL’s 20.1%, 12.5%, 23.8%, and 20.8%, FIX’s 17.1%, 12.8%, 25.7%, and 17.8%, KNX’s 5.2%, 0.6%, 24.3%, and 13.6%, GXO’s 3.0%, 1.0%, 15.3%, and 6.9%, and EXPD’s 10.7%, 7.6%, 13.6%, and 10.5%. The gap is mostly structural and scale-related, because SYM’s gross margin is not far from KNX or EXPD, but its operating and EBITDA margins are far lower, which points to a heavier opex burden rather than a pure cost-of-revenue problem.
Leverage
| Company | Total Debt/Equity % (mrq) | Current Ratio (mrq) | Total Debt (mrq, USD Mil) | Operating Cash Flow TTM (USD Mil) | Free Cash Flow TTM (USD Mil) | Net Debt/EBITDA (TTM) | FCF Margin % (TTM) |
|---|---|---|---|---|---|---|---|
| SYM | 2.3 | 1.3 | 25.8 | 894.4 | 547.6 | -30.4 | 20.7% |
| STRL | 24.2 | 1.1 | 336.8 | 597.7 | 349.4 | -0.2 | 10.2% |
| FIX | 11.5 | 1.2 | 369.9 | 2,550.1 | 1,841.9 | -0.8 | 16.4% |
| KNX | 38.4 | 0.9 | 2,685.2 | 1,391.1 | 491.3 | 2.4 | 6.4% |
| GXO | 202.5 | 0.8 | 6,119 | 509 | 340.6 | 5.7 | 2.5% |
| EXPD | 26.7 | 1.6 | 567.3 | 972.5 | 797.6 | -0.4 | 6.6% |
Source: Yahoo Finance
SYM’s total debt to equity is 2.3%, net debt to EBITDA is negative 30.4x because cash of $1.7B exceeds debt of $25.8M, and FCF margin is 20.7%, versus STRL at 24.2%, -0.2x, and 10.2%; FIX at 11.5%, -0.8x, and 16.4%; KNX at 38.4%, 2.4x, and 6.4%; GXO at 202.5%, 5.7x, and 2.5%; and EXPD at 26.7%, -0.4x, and 6.6%. That cash-rich balance sheet is a real support for the equity, and it is the main reason the valuation does not look as fragile as the revenue multiple alone suggests.
Conclusion
The tension here is simple: Symbotic has a real moat and a strong cash position, but the valuation already assumes that the rollout turns into much better earnings than the company has shown so far. Revenue reached 720.8M in Q2 2026 and levered free cash flow was 547.6M TTM, so the business is scaling and funding itself, yet operating margin is still only 4.6% TTM and the restatement issue reminds me that execution quality still matters as much as growth.
I would raise my rating more toward a Buy if revenue keeps compounding above 700M per quarter and operating margin moves into the high single digits, because that would show the Walmart rollout and the broader installed base are translating into real earnings leverage rather than just top-line growth. If EBITDA margin moved from 2.1% TTM to 6.0%, that would add roughly $110M of annual EBITDA on the current $2.6B revenue base, which would materially improve the path to a lower multiple and make the current valuation easier to defend. I would also want to see the restatement risk fade into the background, because a business this concentrated cannot afford repeated questions about milestone accounting.
I would move from Hold to Sell if revenue growth slips below 15% year over year for two straight quarters or if the restatement and control issues start to affect contract timing. In that case, the market would be left with a rich multiple, a still-concentrated customer base, and less confidence in reported results. A sharper warning sign would be free cash flow falling below $300M over the next twelve months, since that would tell me the current cash generation is not durable enough to support the present valuation.
Weighing both cases, I think the bear case has the earlier path to showing up in the stock because the valuation is already demanding while the earnings base is still thin. The company can grow into the price, but until margin expansion becomes visible in the numbers, I would rather wait than pay ahead of execution.
What to Watch Next
- Revenue above 700M per quarter — would support a more constructive view.
- Operating margin in the high single digits — would argue the rollout is becoming earnings leverage.
- EBITDA margin at 6.0% — would materially improve the valuation case.
- Free cash flow above $300M over the next 12 months — would confirm cash generation is durable.
- Restatement and control issues fading — would reduce the reporting-quality discount.
What’s your take? I rated Symbotic (SYM) HOLD above — but the goal here is to get this right, not just to publish an opinion. What would you add to this analysis, or which risk or catalyst do you think I’m under- or over-weighting? Tell me in the comments.
Sources
- SEC 10-K Annual Report — filed 2024-12-04
- SEC 8-K Filing (2024-11-18)
- SEC 8-K Filing (2024-07-29)
- SEC 8-K Filing (2024-05-06)
- SEC 8-K Filing (2024-03-25)
- SEC 8-K Filing (2024-03-08)
- SEC 8-K Filing (2024-03-04)
- SEC Form 4 Insider Transaction (2026-06-03)
- SEC Form 4 Insider Transaction (2026-06-03)
- SEC Form 4 Insider Transaction (2026-05-29)
- SEC 10-K Annual Report — FY2024
- SEC 10-K Annual Report — FY2023
- SEC 10-K Annual Report — FY2022
Data sourced from Yahoo Finance and SEC EDGAR. Not investment advice.
Leave a Comment