Expected price range
Each range is a ~68% statistical band built from the stock’s own 1-year realised volatility (40% annualised), centred on a path that closes a quarter of the gap to our fair-value midpoint by 3 months and half by 6 months. Starting price $44.39 (close 2026-10-16). This is an illustration of where our view and normal volatility point, not a forecast, price target or investment advice; the stock can move outside it.
| Company | Oct 25 | Nov 25 | Dec 25 | Jan 26 | Feb 26 | Mar 26 | Apr 26 | May 26 | Jun 26 | Jul 26 | Aug 26 | Sep 26 | 12-Mo |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| BSX | +3% | +1% | -6% | -2% | -18% | -18% | -8% | -16% | -12% | +9% | +3% | -10% | -55% |
| MDT | -5% | +16% | -8% | +7% | -5% | -11% | -7% | -9% | +7% | +9% | +6% | -4% | -6% |
| EW | +6% | +5% | -2% | -5% | +6% | -7% | +4% | +4% | +5% | -5% | +5% | -5% | +11% |
| ABT | -7% | +4% | -3% | -12% | +6% | -12% | -11% | -6% | +6% | +17% | +4% | -10% | -25% |
| SYK | -4% | +4% | -5% | +5% | +5% | -15% | -4% | -3% | +3% | +3% | -1% | -15% | -25% |
| ZBH | +2% | -3% | -8% | -3% | +13% | -8% | -9% | -0% | +5% | +9% | +7% | -11% | -9% |
Source: Yahoo Finance monthly adjusted close.
Quick Thesis
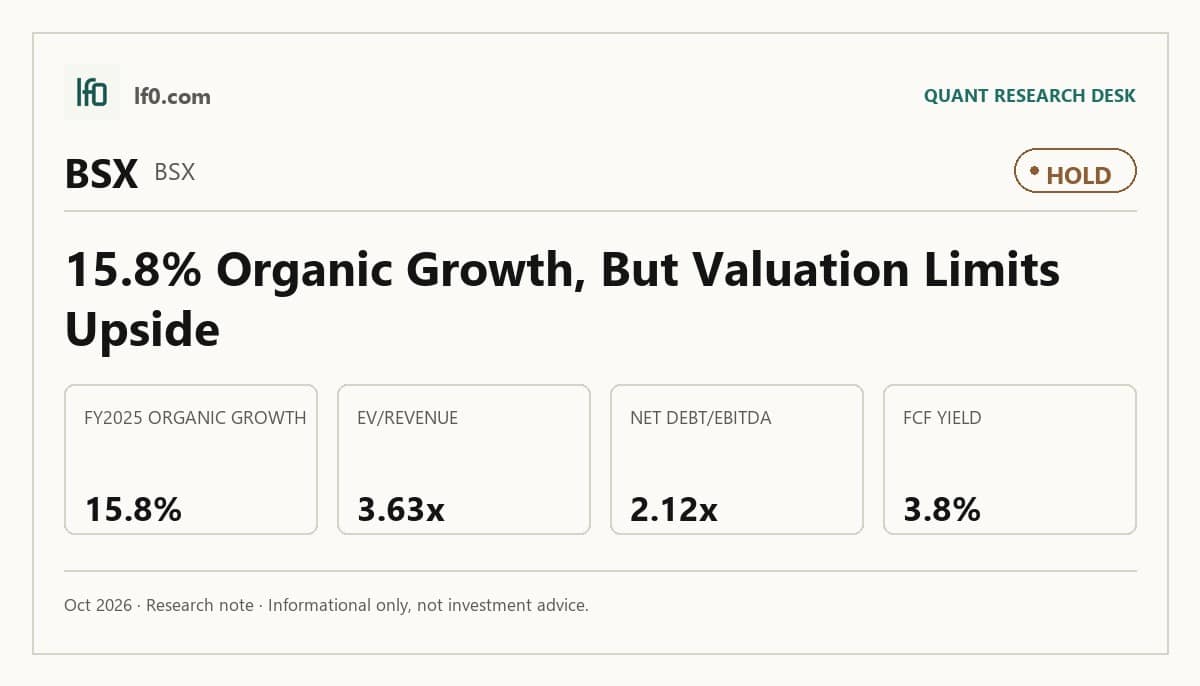
- Rated Hold — growth is solid, but valuation already reflects it.
- Strongest support: 15.8% organic growth in FY2025.
- Main risk: 12.6B of debt ahead of the Penumbra integration.
- Valuation is in-line to slightly rich at 13.4x EV/EBITDA.
- I would turn more constructive if net debt/EBITDA stays below 2.5x, meaning debt does not outrun cash generation.
Executive Summary
Rating: HOLD | BSX
Measured from adjusted close on 2026-10-16 to 2026-10-30. Sell ratings are correct when the stock falls; Hold is tracked as a +/-10% range. Daily-close data, not intraday. Calls are tracked for 182 days from publication, then frozen as a final record.
Earlier calls on this company: BUY from 2026-06-14 to 2026-10-16, -5.1% on the stock. Each earlier call is tracked on its own and stays in our public record; we hold one live position per company at a time.
I would put my rating as a Hold because Boston Scientific has enough growth, margin quality, and balance-sheet capacity to avoid a bearish call, but not enough valuation support or earnings leadership to justify a Buy at 44.1. Revenue growth of 7.5% TTM trails MDT at 13.7%, ABT at 13.0%, and SYK at 9.4%, while FCF yield of 3.8% TTM sits below MDT’s 4.4% and ZBH’s 6.0%, so the stock is not obviously cheap on cash generation either. I would raise my rating more towards a Buy if organic growth re-accelerates toward the low double digits and the company proves it can convert that into a higher FCF margin, because that would close the gap between BSX’s 3.6x EV/Revenue and the richer 4.5x to 4.8x multiples awarded to faster-growing peers.
Company Profile
Boston Scientific develops and sells minimally invasive medical devices used in cardiovascular, respiratory, digestive, oncological, neurological, and urological procedures. It sells stents, catheters, implants, ablation systems, scopes, and remote-monitoring products to hospitals, clinics, outpatient facilities, and medical offices in 127 countries.
The company reports two segments, MedSurg and Cardiovascular, and its portfolio has been reshaped by acquisitions including Bolt Medical and SoniVie in 2025. It also agreed in January 2026 to acquire Penumbra for about $14.5B, a move that would deepen its cardiovascular exposure and add scale in adjacent interventional categories.
Economic Moat
Business Model
Boston Scientific’s moat comes from clinical workflow lock-in. Products such as WATCHMAN left atrial appendage closure devices and the FARAPULSE pulsed field ablation system are embedded in physician training, hospital purchasing, and procedure-room routines, which makes switching costly even when a rival can fund product development.
I feel that this installed base is hard to copy quickly because it combines regulatory history, physician familiarity, and a broad direct-sales footprint across 127 countries. That combination is more durable than a single product cycle and helps explain why the company can keep launching into new procedure areas without starting from zero each time.
Business & Operating Risks
The most material disclosed risk is pricing pressure from customer consolidation and site-of-care shifts. Boston Scientific says in its SEC risk factors that consolidation, tenders, and the move from inpatient settings to outpatient and office-based care can reduce average selling prices and procedure volumes, which would hit both revenue and operating leverage.
A second risk is launch execution. If next-generation products are delayed or fail to win approval, reimbursement, or physician adoption, the company could lose share in categories where refresh cycles matter.
Supply chain and manufacturing concentration are also real threats because some inputs come from single sources and sterilization depends on internal and contract capacity. The disclosed risks do not directly threaten the moat itself, but they do threaten the pace at which that moat converts into sales and margin.
Management Discussion & Analysis
Management is responding to those risks, but not by de-risking the balance sheet. The Penumbra deal and the earlier Bolt Medical and SoniVie acquisitions show a willingness to keep buying growth, while the restructuring program is aimed at simplifying manufacturing and improving efficiency.
That said, the company is still carrying the execution burden of a larger portfolio and a more leveraged capital structure, so the response is offensive rather than defensive. In my view, management is trying to widen the moat through product breadth and clinical depth, but it has not yet removed the pricing and launch risks that could slow the payoff.
Recent Events
The March 28, 2026 disclosure of positive HI-PEITHO and CHAMPION-AF trial results was the clearest thesis-positive event in the period. Those readouts strengthen the cardiovascular franchise because they add clinical support for future launches and reinforce the company’s position in structural heart and rhythm management.
On May 18, 2026, Boston Scientific announced a $1.5B investment in MiRus LLC and an exclusive option to acquire its transcatheter aortic valve replacement assets for up to $3B more if milestones are met. I view that as a strategic extension, but it also adds execution risk because the value depends on clinical and regulatory milestones that are not yet secured.
The same day, the company launched a $2B accelerated share repurchase under its existing $5B authorization, which signals confidence in cash generation. Taken together, the recent events support the moat thesis, but they also show management is choosing to press its advantage rather than pause for balance-sheet repair.
Financial Analysis
Growth
BSX — Financial Growth (Quarterly, USD Mil)
| Metric | 2025-03-31 | 2025-06-30 | 2025-09-30 | 2025-12-31 | 2026-03-31 | 2026-06-30 |
|---|---|---|---|---|---|---|
| REVENUE (USD Mil) | 4,663 | 5,061 | 5,065 | 5,286 | 5,203 | — |
| EBIT (USD Mil) | 887 | 1,031 | 1,026 | 790 | 1,252 | — |
| EBITDA (USD Mil) | 1,212 | 1,367 | 1,368 | 1,155 | 1,603 | — |
| NET INCOME (USD Mil) | 674 | 797 | 755 | 672 | 1,341 | — |
| DILUTED EPS | — | 0.5 | 0.5 | 0.5 | 0.9 | 0.6 |
Source: Yahoo Finance — Quarterly Financial Statements
Boston Scientific’s revenue trend is still expanding, but the pace is uneven. Revenue rose from $4.7B in Q1 2025 to $5.2B in Q1 2026, up 11.6% year over year, while EBITDA increased to $1.6B from $1.2B and net income climbed to $1.3B from $674M. That mix tells me the business is still converting scale into earnings, even though the sequential dip from $5.3B to $5.2B shows the path is not perfectly linear.
The growth profile also fits the moat. A company with embedded clinical workflows should be able to hold share and expand into adjacent procedures, and Boston Scientific’s 15.8% organic growth in FY2025 suggests that advantage is still working.
Profitability
BSX — Profitability (TTM)
| Metric | TTM |
|---|---|
| Operating Margin (TTM) | 22.9% |
| Net Margin (TTM) | 17.5% |
| Return on Assets (TTM) | 6.2% |
| Return on Equity (TTM) | 15.3% |
| Gross Margin (TTM) | 69.2% |
| EBITDA Margin (TTM) | 27.2% |
Source: Yahoo Finance — Trailing Twelve Months (TTM)
TTM operating margin was 22.9%, gross margin was 69.2%, and EBITDA margin was 27.2%. The 46.3-point gap between gross and operating margin shows the business still carries heavy operating expense, so the story is commercial leverage rather than a cost-of-revenue problem.
Net margin was 17.5%, while ROA was 6.2% and ROE was 15.3%. That spread tells me the company is producing respectable returns, but leverage is helping those returns more than pure asset efficiency is.
Valuation
BSX — Valuation Multiples
| Metric | Value |
|---|---|
| Current Share Price (USD) | 44.1 |
| Market Cap (USD Mil) | 63,969 |
| Enterprise Value (USD Mil) | 76,296 |
| Trailing P/E | 17.9 |
| Forward P/E | 13.1 |
| Price/Sales (TTM) | 3 |
| Price/Book (mrq) | 2.6 |
| EV/Revenue | 3.6 |
| EV/EBITDA | 13.4 |
| Beta (5Y Monthly) | 0.57 |
| FCF Yield % (TTM) | 3.8% |
| Forward EPS (USD) | 3.4 |
| Analyst Target Price – Low (USD) | 44 |
| Analyst Target Price – Mean (USD) | 59.2 |
| Analyst Target Price – High (USD) | 94 |
| # Analyst Opinions | 29 |
Source: Yahoo Finance
Boston Scientific trades at 3.6x EV/Revenue, 13.4x EV/EBITDA, 17.9x trailing P/E, and 13.1x forward P/E, with a 3.8% FCF yield. On those numbers, I do not see a deep discount; the market is paying for a durable med-tech platform, but not for top-tier growth.
On the analysis here, I would put fair value in a range of $44–$59. That range sits roughly inside the analyst consensus band of $44–$94, but below the $59.2 mean because I weight the slower 7.5% revenue growth and the 2.1x net debt/EBITDA more heavily than the consensus seems to. Forward EPS of 3.38 also implies a reasonable earnings base, but it is not rich relative to peers with stronger margins and faster sales growth.
The valuation picture is tied to leverage. Boston Scientific’s lower EV/Revenue than EW and SYK is justified by weaker growth and a less efficient cash conversion profile, so I do not think the stock deserves a premium multiple until the Penumbra integration proves it can add earnings faster than it adds debt.
Leverage
BSX — Leverage & Coverage (Quarterly)
| Metric | Value |
|---|---|
| Total Debt/Equity % (mrq) | 50.2 |
| Current Ratio (mrq) | 1.2 |
| Total Debt (mrq, USD Mil) | 12,624 |
| Operating Cash Flow (TTM, USD Mil) | 4,529 |
| Levered Free Cash Flow (TTM, USD Mil) | 2,451.4 |
| Net Debt/EBITDA (TTM) | 2.1 |
| FCF Margin % (TTM) | 11.7% |
Source: Yahoo Finance — Quarterly Financial Statements
Boston Scientific’s leverage is moderate, not stretched. Total debt/equity was 50.2%, current ratio was 1.2, and total debt was $12.6B, while total cash was $539M. On a cash-flow basis, operating cash flow was $4.5B and levered free cash flow was $2.5B, with net debt/EBITDA at 2.1 and FCF margin at 11.7%.
That is manageable, but it is not a free pass. The company can absorb a normal operating slowdown, yet the debt load leaves less room for error if reimbursement pressure or integration costs run hotter than expected.
Insider Activity
The insider record is net buying, but only narrowly. There were 5 open-market purchases totaling $558,514 versus 40 open-market sales totaling $99.1M, so the broader pattern is still clearly net selling.
The buying is concentrated in a few directors, which tells me confidence exists at the board level but is not broad-based. I would not read this as a strong signal either way.
Comparable Analysis
LF0 has published standalone analyses of these peers: Stryker (SYK) (rated Hold).
Growth
| Company | Revenue TTM (USD Mil) | Revenue Growth YoY % | EBITDA TTM (USD Mil) | Diluted EPS TTM |
|---|---|---|---|---|
| BSX | 20,996 | 7.5% | 5,711 | 2.5 |
| MDT | 37,542 | 13.7% | 10,408 | 4.1 |
| EW | 6,512.3 | 13.6% | 1,996.8 | 1.7 |
| ABT | 46,585 | 13.0% | 11,681 | 3.1 |
| SYK | 25,837 | 9.4% | 7,376 | 10 |
| ZBH | 8,508.8 | 4.8% | 2,525 | 4.1 |
Source: Yahoo Finance
Boston Scientific’s 7.5% revenue growth TTM trails MDT at 13.7%, EW at 13.6%, ABT at 13.0%, and SYK at 9.4%, while ZBH is slower at 4.8%. That gap matters because it means BSX is not winning on growth leadership, so any valuation support has to come from profitability and cash conversion instead.
Valuation
| Company | Current Share Price (USD) | Trailing P/E | Forward P/E | EV/Revenue | EV/EBITDA | Price/Sales (TTM) | Price/Book (mrq) | Market Cap (USD Mil) | Enterprise Value (USD Mil) | Beta (5Y Monthly) | FCF Yield % (TTM) | Forward EPS | Analyst Target Price – Low | Analyst Target Price – Mean | Analyst Target Price – High | # Analyst Opinions |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| BSX | 44.1 | 17.9 | 13.1 | 3.6 | 13.4 | 3 | 2.6 | 63,969 | 76,296 | 0.57 | 3.8% | 3.4 | 44 | 59.2 | 94 | 29 |
| MDT | 95.4 | 23.5 | 14.9 | 3.8 | 13.6 | 3.3 | 2.4 | 122,094 | 142,046 | 0.57 | 4.4% | 6.4 | 85 | 104.4 | 121 | 25 |
| EW | 88.1 | 52.4 | 26.1 | 7.3 | 23.7 | 7.8 | 4.8 | 50,728 | 47,339 | 0.86 | 2.4% | 3.4 | 84 | 101.8 | 110 | 26 |
| ABT | 104.7 | 33.8 | 17.3 | 4.5 | 17.9 | 3.9 | 3.5 | 182,333 | 208,906 | 0.58 | 4.0% | 6.1 | 103 | 120.7 | 135 | 26 |
| SYK | 293.2 | 29.3 | 17.6 | 4.8 | 16.9 | 4.4 | 4.7 | 112,475 | 124,445 | 0.78 | 3.6% | 16.7 | 298 | 362.6 | 465 | 26 |
| ZBH | 94.4 | 22.9 | 10.4 | 3 | 10 | 2.1 | 1.4 | 18,002 | 25,148 | 0.48 | 6.0% | 9.1 | 93 | 106.8 | 130 | 22 |
Source: Yahoo Finance
BSX trades at 3.6x EV/Revenue, 13.4x EV/EBITDA, and 3.8% FCF yield, versus MDT at 3.8x, 13.6x, and 4.4%, ABT at 4.5x, 17.9x, and 4.0%, SYK at 4.8x, 16.9x, and 3.6%, and ZBH at 3.0x, 10.0x, and 6.0%. On a growth-adjusted basis, BSX looks more fairly priced than cheap: it is not paying the richest multiple in the group, but it also is not offering the best cash yield.
Using peer EV/Revenue of 3.0x to 7.3x on BSX’s $21B TTM revenue gives an illustrative enterprise value of about $62.2B to $152.7B, or roughly $34.4 to $103.3 per share after netting $12.1B of net debt and dividing by 1.449B shares. That range is wide enough to show upside, but the current 44.1 share price already sits above the low end, so I do not see a clear bargain.
Profitability
| Company | Operating Margin (TTM) | Net Margin (TTM) | Return on Assets (TTM) | Return on Equity (TTM) | Gross Margin (TTM) | EBITDA Margin (TTM) |
|---|---|---|---|---|---|---|
| BSX | 22.9% | 17.5% | 6.2% | 15.3% | 69.2% | 27.2% |
| MDT | 19.3% | 13.9% | 5.1% | 10.6% | 65.3% | 27.7% |
| EW | 29.8% | 15.4% | 8.4% | 9.2% | 77.8% | 30.7% |
| ABT | 14.7% | 11.6% | 5.3% | 10.6% | 56.9% | 25.1% |
| SYK | 27.0% | 14.4% | 8.2% | 16.5% | 65.6% | 28.5% |
| ZBH | 18.0% | 9.5% | 3.9% | 6.4% | 69.5% | 29.7% |
Source: Yahoo Finance
BSX’s 22.9% operating margin and 27.2% EBITDA margin are solid, but EW’s 29.8% and 30.7% and SYK’s 27.0% and 28.5% are better. BSX does beat MDT on operating margin and sits well above ABT on gross margin, which tells me the company is competitive, just not best in class.
Leverage
| Company | Total Debt/Equity % (mrq) | Current Ratio (mrq) | Total Debt (mrq, USD Mil) | Operating Cash Flow TTM (USD Mil) | Free Cash Flow TTM (USD Mil) | Net Debt/EBITDA (TTM) | FCF Margin % (TTM) |
|---|---|---|---|---|---|---|---|
| BSX | 50.2 | 1.2 | 12,624 | 4,529 | 2,451.4 | 2.1 | 11.7% |
| MDT | 55.4 | 2.1 | 28,153 | 8,035 | 5,412.5 | 1.9 | 14.4% |
| EW | 6.6 | 4.5 | 704.4 | 1,720.3 | 1,232.4 | -1.8 | 18.9% |
| ABT | 63.2 | 1.4 | 32,720 | 9,905 | 7,209.1 | 2.3 | 15.5% |
| SYK | 64.4 | 2.2 | 15,446 | 5,525 | 4,108.9 | 1.6 | 15.9% |
| ZBH | 60.2 | 1.7 | 7,601.7 | 1,743.3 | 1,072.2 | 2.8 | 12.6% |
Source: Yahoo Finance
BSX’s 2.1x net debt/EBITDA is higher than EW’s -1.8x and MDT’s 1.9x, but below ABT’s 2.3x and ZBH’s 2.8x. Its 11.7% FCF margin is also below MDT, EW, ABT, and SYK, which explains why the market is not awarding BSX a premium multiple for balance-sheet safety.
Conclusion
I would put my rating as a Hold because the core tension is now clear: Boston Scientific has a real moat and decent earnings power, but the stock already discounts much of that quality while the balance sheet is about to get more demanding. The business is still growing, margins are healthy, and the recent clinical readouts support the franchise, yet the market is not paying a deep discount for those strengths.
I would raise my rating more towards a Buy if organic growth re-accelerates toward the low double digits and the company shows that the Penumbra deal can lift forward EPS above 3.4 while keeping net debt/EBITDA below 2.5x, meaning debt is still being covered comfortably by cash generation. That would tell me the acquisition is adding earnings faster than it is adding risk, which is the key test for a higher multiple.
The bear case is the opposite: if growth stays in the mid single digits, FCF yield slips below 3.0%, and leverage moves above 2.5x net debt/EBITDA, I would move from Hold to Sell because the stock would be asking investors to pay for growth that is not showing up fast enough. In that scenario, reimbursement pressure and integration costs would start to matter more than the moat.
For now, I think the bull case is more likely to arrive later than the market wants, while the downside can show up quickly if execution slips. That leaves me with a Hold: good business, acceptable valuation, but not yet enough evidence that the next leg of earnings growth will outrun the added capital burden.
What to Watch Next
- Organic growth back toward the low double digits — would support a move toward Buy.
- Forward EPS above 3.4 — would show the Penumbra deal is adding earnings.
- Net debt/EBITDA below 2.5x — would keep leverage manageable after the acquisition.
- FCF yield above 4.0% — would improve the case for a higher multiple.
- Revenue growth staying above 8% — would help offset reimbursement and pricing pressure.
Update Since Our Last Call
Rating changed: Buy (2026-06-14) → Hold (today). Stock return since our prior call: -5.6% (Incorrect so far).
The prior thesis has played out poorly so far: the stock return since entry was -5.6%, and the verdict is Incorrect so far. I was too early on the Buy call.
What genuinely changed is that the new piece puts much more weight on leverage and valuation. It cites “$12.6B of debt ahead of the Penumbra integration,” “13.4x EV/EBITDA,” and a “3.8% TTM” FCF yield, whereas the prior article leaned on “14.5x EV/EBITDA,” “12.6x forward P/E,” and “TTM levered free cash flow of $2,807.1M.” The new article also adds the March 28, 2026 HI-PEITHO and CHAMPION-AF readouts, plus the May 18, 2026 $1.5B MiRus investment and the $2B accelerated share repurchase, none of which were in the prior write-up.
What stayed the same is the core moat view and the recurring reimbursement risk. Both articles independently confirm the installed-base advantage across Boston Scientific’s interventional franchises and the pressure from pricing, consolidation, and site-of-care shifts. Both also agree that the business is still growing and converting that growth into cash.
On valuation, the prior article gave no explicit fair-value range, while the new article says, “I would put fair value in a range of $44-$59.” So the only explicit range is the new one, and it is lower than the prior article’s more constructive stance because the new evidence emphasizes slower “7.5% revenue growth TTM,” “3.8% FCF yield,” and “2.1x net debt/EBITDA.” The ratings are different too: prior Buy versus new Hold, and I now weight the leverage and cash-yield evidence more heavily.
What’s your take? I rated Boston Scientific (BSX) HOLD above — but the goal here is to get this right, not just to publish an opinion. What would you add to this analysis, or which risk or catalyst do you think I’m under- or over-weighting? Tell me in the comments.
Sources
- SEC 10-K Annual Report — filed 2026-02-17
- SEC 8-K Filing (2026-05-18)
- SEC 8-K Filing (2026-05-18)
- SEC 8-K Filing (2026-05-05)
- SEC 8-K Filing (2026-04-22)
- SEC 8-K Filing (2026-03-30)
- SEC 8-K Filing (2026-02-26)
- SEC Form 4 Insider Transaction (2026-06-01)
- SEC Form 4 Insider Transaction (2026-05-21)
- SEC Form 4 Insider Transaction (2026-05-21)
- SEC 10-K Annual Report — FY2026
- SEC 10-K Annual Report — FY2025
- SEC 10-K Annual Report — FY2024
- SEC 10-K Annual Report — FY2023
- SEC 10-K Annual Report — FY2022
Data sourced from Yahoo Finance and SEC EDGAR. Not investment advice.
Leave a Comment